
Table of Contents
Understanding the Threat of Fraud
As a business owner, you know that financial success is key to keeping your doors open. Unfortunately, scammers are adopting new technology and more advanced methods to commit fraud, leading to possible financial loss and reputational damage to your business. A scam becomes fraud when deceit is used to obtain a benefit or cause a loss by deception or other means. Committing fraud is a criminal offense, and it can have severe consequences for both the perpetrator and the victim.
Data from the latest ACCC Targeting Scams report revealed a 73% increase in scam losses across the Australian business community in 2022, totaling $23.2 million. This alarming statistic highlights the importance of implementing scam and fraud prevention measures. One of the challenges of fraud prevention in the digital age is that scammers have new tools and tactics at their disposal. For example, phishing scams and fake invoices are common ways that criminals can trick businesses into sending them money. These scams often involve sophisticated techniques that can be difficult to detect, such as creating fake websites or email addresses that closely resemble legitimate ones.
In addition, cyber-attacks can compromise sensitive data, leaving businesses vulnerable to financial loss. Hackers can gain access to your company’s financial information, customer data, and other critical assets, which they can then use to commit fraud. The rise of ransomware attacks, where hackers demand payment in exchange for releasing encrypted data, is another growing threat. As technology continues to evolve, so do the methods used by scammers, making it essential for businesses to stay vigilant and proactive in their scams prevention efforts.
Identifying Red Flags and Implementing Procedures
o protect your business, it’s important to look out for red flags that could indicate scams. These could include unexplained discrepancies in financial records, suspicious transactions, or employees who refuse to take time off or share their work with others. Additionally, be wary of unexpected requests for money or changes to payment procedures. Scammers often rely on creating a sense of urgency or secrecy to manipulate their victims, so any unusual or urgent requests should be treated with caution.
To prevent and detect scams, there are a few key procedures you should implement. First, have clear policies and procedures in place for financial transactions, including who has access to sensitive information and how payments should be made. Establishing a system of checks and balances can help ensure that no single employee has too much control over financial processes. Use secure payment methods and regularly review financial records for irregularities. Implementing strong internal controls, such as requiring dual authorization for large transactions, can help prevent unauthorized payments.
You should also conduct background checks on new employees and have a system for reporting suspected scams. Hiring trustworthy employees is crucial, as insider scams can be particularly damaging. Regularly updating your fraud prevention policies and providing ongoing training for employees can help keep everyone informed about the latest threats and best practices. Educating your employees on fraud prevention and detection is also important. This could include training on how to identify and report suspicious activity, as well as how to follow company policies and procedures. Make sure all employees understand the importance of following security protocols, and regularly review these protocols to ensure they are up-to-date and effective.
Securing Your Business Against Fraud
Finally, review your insurance policies to make sure you have coverage for potential losses due to fraud. This can include crime insurance, which can help cover losses related to theft or scams, as well as cyber insurance, which can help cover losses related to data breaches or other cyber-attacks. Having the right insurance coverage can provide a financial safety net in the event that your business falls victim to scams.
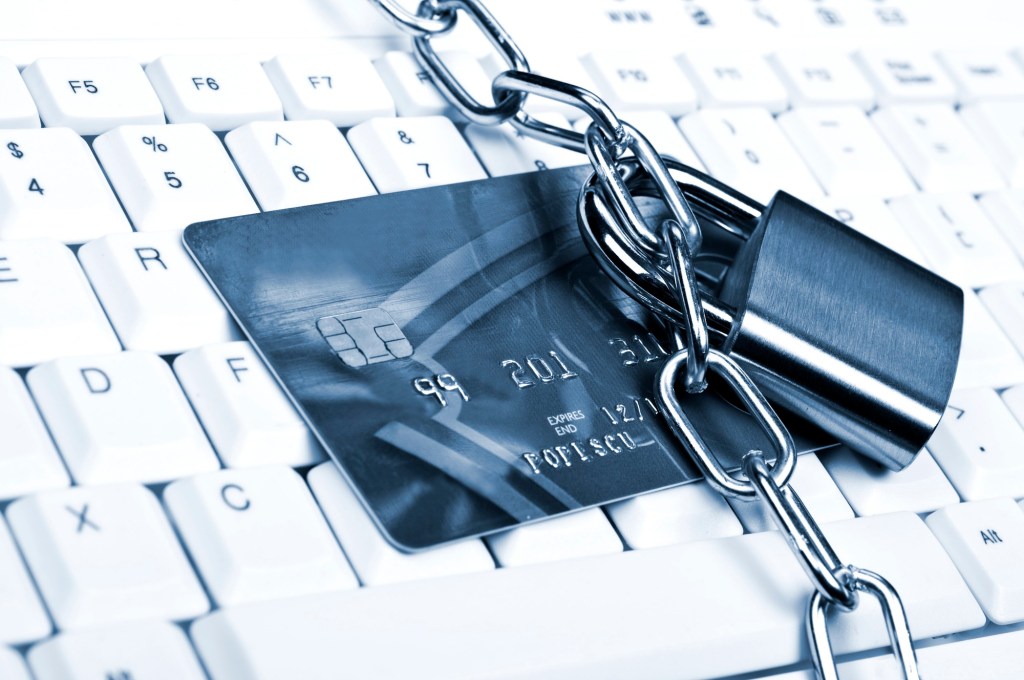
To protect your business from fraud, it’s crucial to take proactive measures such as looking out for red flags, implementing financial transaction procedures, educating your employees, and reviewing your insurance policies. By following these steps, you can help ensure the safety and security of your business. Additionally, consider investing in advanced security technologies, such as encryption and multi-factor authentication, to further protect your sensitive data.
If you have any questions or concerns about fraud prevention and detection, contact your accountant for assistance. They can help you develop effective policies and procedures, as well as review your financial records for irregularities. Taking these steps can significantly reduce the risk of fraud and help maintain the financial health and reputation of your business. Remember, staying informed and vigilant is key to safeguarding your business against the ever-evolving threat of fraud.
Always speak to experts to make sure you’re finances are secure.